Failed Gym Payments: Stop Hard Declines, Recover Soft Ones

Turn on targeted retries and automated dunning, give members a self-service link and a backup payment method, and stop retrying hard declines the moment they appear. Gyms that combine those steps may win back missed dues. Start today: check your processor’s retry settings, activate dunning emails, and add a payment update link.
TL;DR:
- Retry soft declines only a few times, spacing attempts around likely paydays; stop immediately for closed, lost, stolen, invalid, or revoked payment credentials.
- Send the first notice within hours with the amount due and a hosted update link, then follow up by email, text, or app notification.
- For bank debits, give 10 days’ notice before changing recurring dates or amounts, and count funds as settled only after return windows close.
- Review recovery rate, top decline reasons, and balances past 30 days monthly; set alert thresholds from your baseline and investigate sharp changes.
- Refer accounts only after dunning ends, the balance clears your amount floor, reminders go unanswered, and a signed agreement covers the debt.
Getfitnessflow
Keep Gym Billing Under Control
Fitness Flow brings billing, scheduling, sales, and member engagement together in one gym management platform, helping streamline operations.
Table of Contents
- Why do gym membership payments fail in the first place?
- Which decline codes should you retry, and which should you never touch?
- What does a plug-and-play dunning workflow look like?
- How do you make it easy for members to fix a failed payment themselves?
- What do ACH and NACHA rules mean for recurring gym debits?
- Which reports and KPIs show whether recovery is working?
- When should you keep recovering and when should you escalate to collections?
- An editorial view: three priorities for the next 30 days
- How we automate retry logic, dunning, and member self-service
- FAQ
- Sources
Why do gym membership payments fail in the first place?
Most failed payments are not a member deciding to quit. They are plumbing problems you can fix, and knowing which ones hit you hardest tells you where to spend your effort first.
The usual causes look like this:
- Expired or reissued cards. A bank replaces a card after fraud or at expiry, and the old number stops working. This is permanent until the member supplies a new credential.
- Insufficient funds. The account is short on billing day. This is transient, so a well-timed retry often works.
- Incorrect billing details. A wrong ZIP code or a changed address trips verification checks.
- Issuer fraud flags. The bank blocks a recurring charge it does not recognize. Sometimes a retry clears it; sometimes the member has to call the bank.
- Customer-initiated stops. The member disputes the charge or revokes authorization. Retrying here only creates friction.
Sort these into two buckets. Transient causes (low balance, temporary issuer holds) deserve retries. Permanent causes (closed account, expired card, revoked authorization) need a new credential from the member.
To see which causes drive your own failures, export a month of billing logs and group every failure by decline reason. A gym with a spike in expiry-related declines has a different fix than one dominated by low balances. Do this before you change any settings, so you have a baseline to measure against.

Which decline codes should you retry, and which should you never touch?
Issuer response codes split into two families. Hard declines are “never-approve” responses: the card is closed, lost, stolen, or the account does not exist. Soft declines are transient: insufficient funds, a temporary issuer problem, or a velocity limit. Issuer response codes separate these two groups, and your retry rules should follow that split.
The operating rules are simple. Suppress retries on never-approve codes immediately. For soft declines, use limited retries spaced around likely paydays rather than hammering them in a single afternoon. Over-retrying costs you in processor fees and exposes you to card network penalty programs, including Visa’s Risk Acceptance Framework and Mastercard’s MAC guidance, which target excessive or inappropriate retry behavior.
Decline typeTypical meaningRetry?Action
Hard decline
Closed account, lost or stolen card, invalid number
No
Stop retries, request a new payment method
Soft decline
Insufficient funds, temporary issuer issue
Yes, use limited retries
Space attempts around pay cycles
Authorization revoked
Member stopped the payment
No
Contact the member, confirm status
Pro Tip: Keep a negative list of cards that returned hard declines, and check every scheduled charge against it before submitting. A single suppressed retry costs nothing; a pattern of repeated hard-decline attempts can cost you in network penalties.
What does a plug-and-play dunning workflow look like?
Dunning is the sequence of reminders and retries that runs after a failed charge. A good one recovers money without making members feel hunted. Our dunning email walkthrough goes deeper on templates, but the skeleton is below.
- When the charge fails: Send the first email right away with a plain explanation and an update link.
- After the first message: Retry the soft decline and note the result.
- Day 3 to 5: Send email 2 and retry again, ideally near a common payday.
- As the sequence continues: Send a short text or app notification with the same link.
- At the end of the sequence: Send a final notice and apply the member-impact step you chose, such as a freeze or pause.
Every message should carry the same three things:
- The amount owed and the date it was due
- A one-click link to update the card or pay the balance
- A line telling the member how to reach you if something looks wrong
Decide your grace period and late-fee policy before you build the sequence, not during it. A short, clearly stated grace window keeps good members from feeling punished over a one-time bank glitch. Restrict access only at the end of the sequence, and restore it the moment the balance clears. Members who lose access on day two tend to cancel; members who get a friendly nudge and a working link tend to stay.
How do you make it easy for members to fix a failed payment themselves?
Every extra step between “your payment failed” and “payment fixed” loses you members. The goal is a message that makes it easy for a member to go from inbox to updated card.
- Send the first email within hours, not days. The member still remembers signing up and is most likely to act.
- Use a hosted payment page. Stripe’s automatic collection tools include Smart Retries, failed-payment emails, and hosted invoice pages, which cut manual follow-up considerably. Note that Stripe does not automatically retry many non-card payment methods by default, so confirm what your setup covers.
- Back up with SMS or an app push. Many members never open the email, but they read texts.
- Turn on card-updater services where your processor offers them, so reissued cards refresh without the member lifting a finger.
- Ask for a backup payment method at signup. Frame it as protection: “Add a second card so your membership never lapses by accident.”
Pro Tip: Put the amount and the update link in the first two lines of every message. Members skim, and a link buried under three paragraphs gets ignored.
If you run recurring debits through a platform, our guide on Stripe products for gym dues explains which pieces map to which billing jobs. Other membership businesses face the same issue; this direct-debit billing article from KWOON covers how small clubs handle automated debits and member communication.
What do ACH and NACHA rules mean for recurring gym debits?
If you pull dues straight from bank accounts, ACH rules apply on top of your own policies. The practical constraints are short enough to memorize.
- Notice of changes. NACHA rules require at least 10 days’ notice before you change the date or amount of a recurring debit.
- Authorization records. Check the applicable ACH rules and your processor’s guidance for how long to keep signed authorizations.
- Return timing. Many ACH returns arrive within the return window, and processors often hold inbound funds until return windows close. Reconcile accordingly, and do not count the money as settled until the return window has passed.
- Combined retry logic. Treat ACH returns as their own track. A return for insufficient funds can follow a similar spaced-retry pattern, but a return for a revoked authorization or closed account should end retries at once.
Build one billing plan that routes card failures and ACH returns into the same dunning sequence, with separate retry rules for each. Our overview of FTC-compliant recurring gym billing covers the authorization and disclosure side, and the 30-day recurring payments checklist helps you get it live.
Which reports and KPIs show whether recovery is working?
You cannot improve what you do not measure. Run these on a fixed schedule so changes in your settings show up in the numbers.
- Recovery rate: the share of failed charges you eventually collect.
- Involuntary churn rate: members lost to payment failure rather than choice.
- Decline reason breakdown: how failures split across expiry, funds, and issuer blocks.
- Accounts receivable aging: unpaid dues grouped by days past due.
- Time to recover: how many days pass between failure and payment.
Read the changes like a mechanic reads gauges. A jump in expiry declines points to an easy fix: schedule expiry reminder campaigns 30 days before cards lapse. A rise in hard declines suggests members are leaving or cards are being reissued in bulk. Slow time-to-recover means your first message is arriving too late or your link has too much friction.
Review a short dashboard monthly: recovery rate trend, top three decline reasons, and anything sitting past 30 days. Set your own alert thresholds based on your baseline, and investigate whenever a metric moves sharply from it. Pair the payment data with attendance. Our win-back email approach tied to attendance helps separate members who forgot to update a card from those drifting away.
When should you keep recovering and when should you escalate to collections?
Treat the initial recovery period as a time for automation and friendly reminders. Collections is a different tool for longer-term debts and repeat nonpayment, with legal and accounting overhead you should not take on lightly.
A practical escalation policy:
- Set a days-past-due line. Escalate only after the dunning sequence is finished and the balance is well past your recovery window.
- Set an amount floor. Small balances rarely justify collection fees; write them off or leave them to automation.
- Flag repeat offenders. A member who has failed several times and ignored every message is a stronger candidate than a first-time failure.
- Check the contract. Confirm a signed agreement exists and covers the amount before you refer anything.
- Prepare the file. A collections partner will want the signed agreement, the billing history, proof of each notice sent, and current contact details.
Keep notes on every contact attempt. Clean records protect you and protect the member relationship if the account is disputed later.
An editorial view: three priorities for the next 30 days
Most gyms do not have a payment problem so much as a follow-up problem. Money sits unpaid because nobody retried at the right moment or the member could not find a link. I would start by setting a retry policy with hard-decline suppression, turning on dunning messages with hosted links and a prompt for backup cards, and tracking recovery rate so the decline-code mix tells me what to fix next.
— Louis
How we automate retry logic, dunning, and member self-service
We built Fitness Flow to help you manage your gym in one platform. We bring gym management together in the same platform that runs your classes and member app.
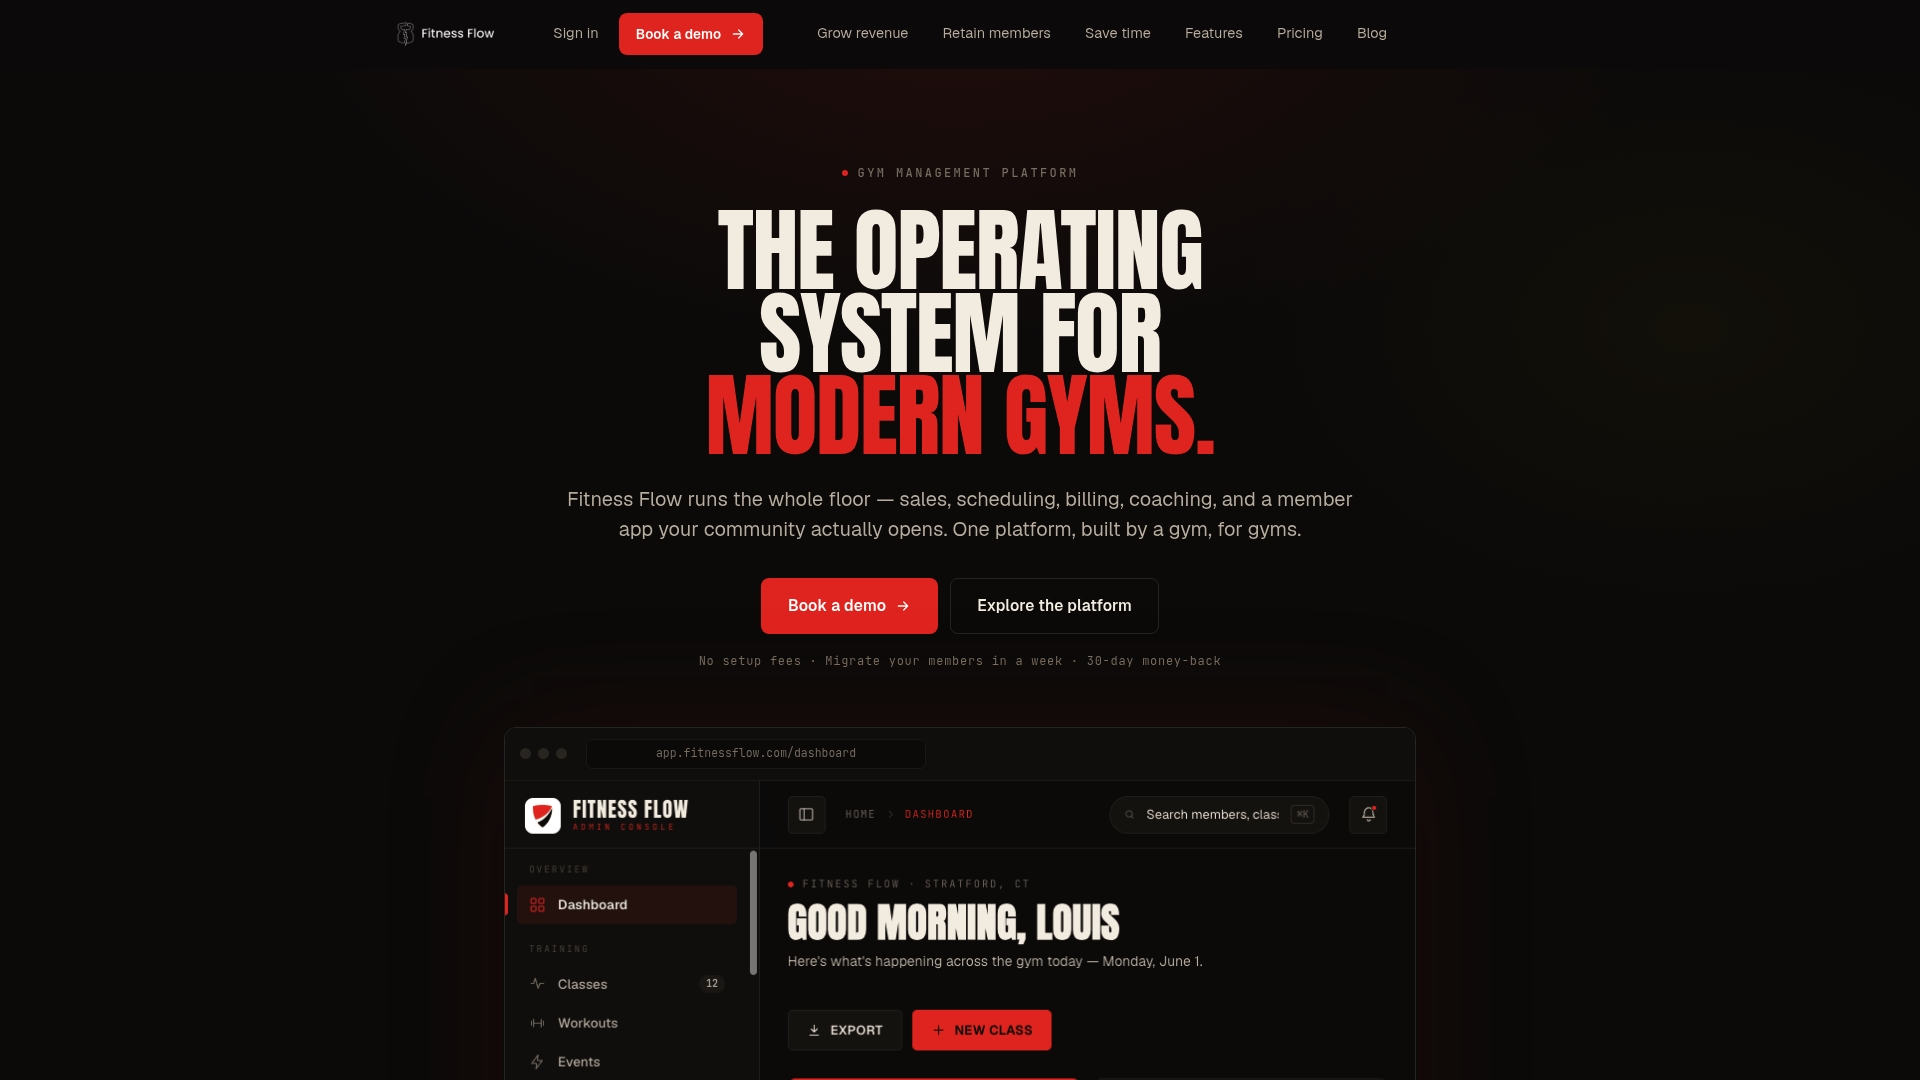
- We help streamline gym operations.
- We help streamline gym operations.
- We provide reporting and analytics to help you make data-driven decisions.
- Your branded member app keeps members engaged while billing runs quietly in the background.
See how it fits your gym on our Fitness Flow for gyms page or request a demo and we will walk you through setup.
FAQ
What happens if a member misses a gym payment?
The charge fails, and your billing system should start retries and reminder messages. If the balance stays unpaid after your grace period, you can restrict access or freeze the membership until it clears.
Do unpaid gym memberships go to collections?
They can, but only when you choose to escalate. Most gyms recover missed dues through automated dunning first and refer accounts only after a long delinquency and a signed agreement is on file.
Should you retry every failed gym payment?
No. Retry soft declines such as low balances a few times, spaced around pay cycles. Never retry hard declines like closed accounts, because that adds fees and network penalty risk.
How soon should the first failed-payment message go out?
Send it right away, ideally within hours of the failure. An early message with a one-click update link reaches the member while the membership is still top of mind.